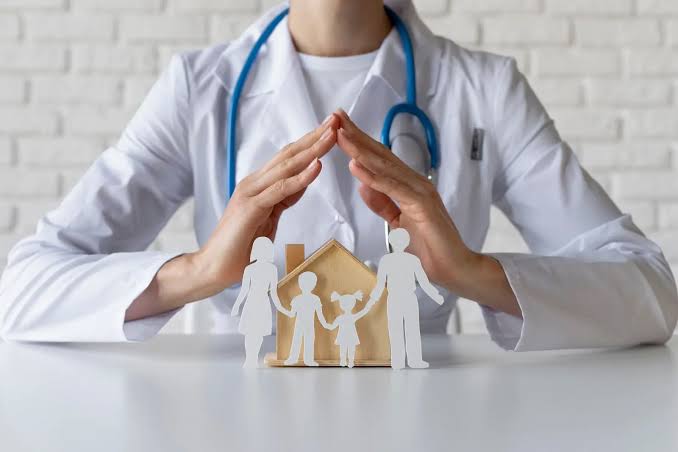
Newborn babies are delicate and face several vulnerabilities to complicated health risks such as organ immaturity, birth complications, and more. That is why a health insurance policy may be essential to protect health coverage for newborns.
Newborn health insurance acts as a protective shield so you do not compromise your baby’s health for finances. However, parents must consider several factors such as waiting periods, included facilities, and more before purchasing newborn health insurance.
Read this article to understand critical factors to consider before purchasing a health insurance policy for newborns in detail.
Which Critical Factors Parents Must Consider for Newborn Health Insurance?
The inclusion criteria in the package, Neonatal Intensive Care Unit (NICU) stays, and other factors parents must consider before choosing a health insurance policy for newborns.
1. Waiting Periods
Standard health insurance policies such as maternity health insurance do not cover infants immediately after birth. These plans typically impose a 30- to 90-day waiting period for the baby, exposing parents to substantial out-of-pocket expenses if health complications occur. You may choose your insurer wisely and consider a low waiting period.
- Family floater plans also include baby coverage after 90 days.
- You may opt for day-1 coverage riders that act as maternity add-ons covering the baby from the very first hour of birth.
2. The Intimation Window
Insurers do not include babies immediately at birth in the floater plans. The policyholder has to inform the insurer during the pregnancy period. Otherwise, parents have to include their child in the floater plan at the next renewal.
- You must complete the paperwork before your child is born.
- You must know the intimation window to add your newborn to the plan at the right time.
3. Congenital Anomalies and NICU Stays
Newborns may face birth complications and require special observation in the NICU unit. Brief phototherapy and advanced care may cause the budget to exceed policyholders’ limits. That is why the policyholder must ensure the policy covers structural or functional disorders.
- Before purchasing the policy, check the policy paper for room-rent restrictions, sub-limits, or ICU and NICU caps.
- You may ask your insurer about details of congenital conditions.
4. Sum Insured Pool
Adding a new member to your existing family floater policy may share the overall sum assured. Since newborns frequently face health vulnerabilities, parents must ensure the sum assured is large enough to cover the entire family. For instance, if 2 people share a ₹5 lakh sum assured in a year, it may not be enough to add another member within the same sum.
- When adding your newborn to the policy, you may increase the overall sum assured.
- You may also purchase a standalone super top-up policy while adding your newborn.
5. Routine Pediatric Care
In the very first year of age, a child undergoes several medical interventions such as vaccinations and check-ups. Although major hospitalisations are infrequent, routine paediatric care costs escalate quickly.
- Check if the policy covers vaccines prescribed by the Indian Academy of Paediatrics.
- Ask your insurer about the outpatient (OPD) expenses to offset the costs of regular paediatrician consultations.
Do you know why to purchase a newborn health insurance policy? It is because parents can find peace of mind and enjoy parenthood moments, forgetting the financial burden. Your baby is your priority. Securing newborn health insurance early protects you from unexpected medical costs, ensuring you never have to compromise on their health.
However, choose your insurer wisely, considering factors such as waiting period, sum assured, coverage, and more. You may opt for Bajaj General Insurance for your newborn for maximum coverage at an affordable premium.
Bottom Line
Securing a newborn health cover ensures comprehensive medical protection for your child without financial strain. Parents can ensure their baby receives the best possible treatment and medical care.
Research your insurer thoroughly regarding the claim settlement ratio, reputation, and competitive pricing. Also check the portfolio and reviews for trust. Review the policy documents and terms and conditions thoroughly so you do not miss any exclusion and inclusion criteria.